A vacation home of your own. Without 30 years of mortgage.
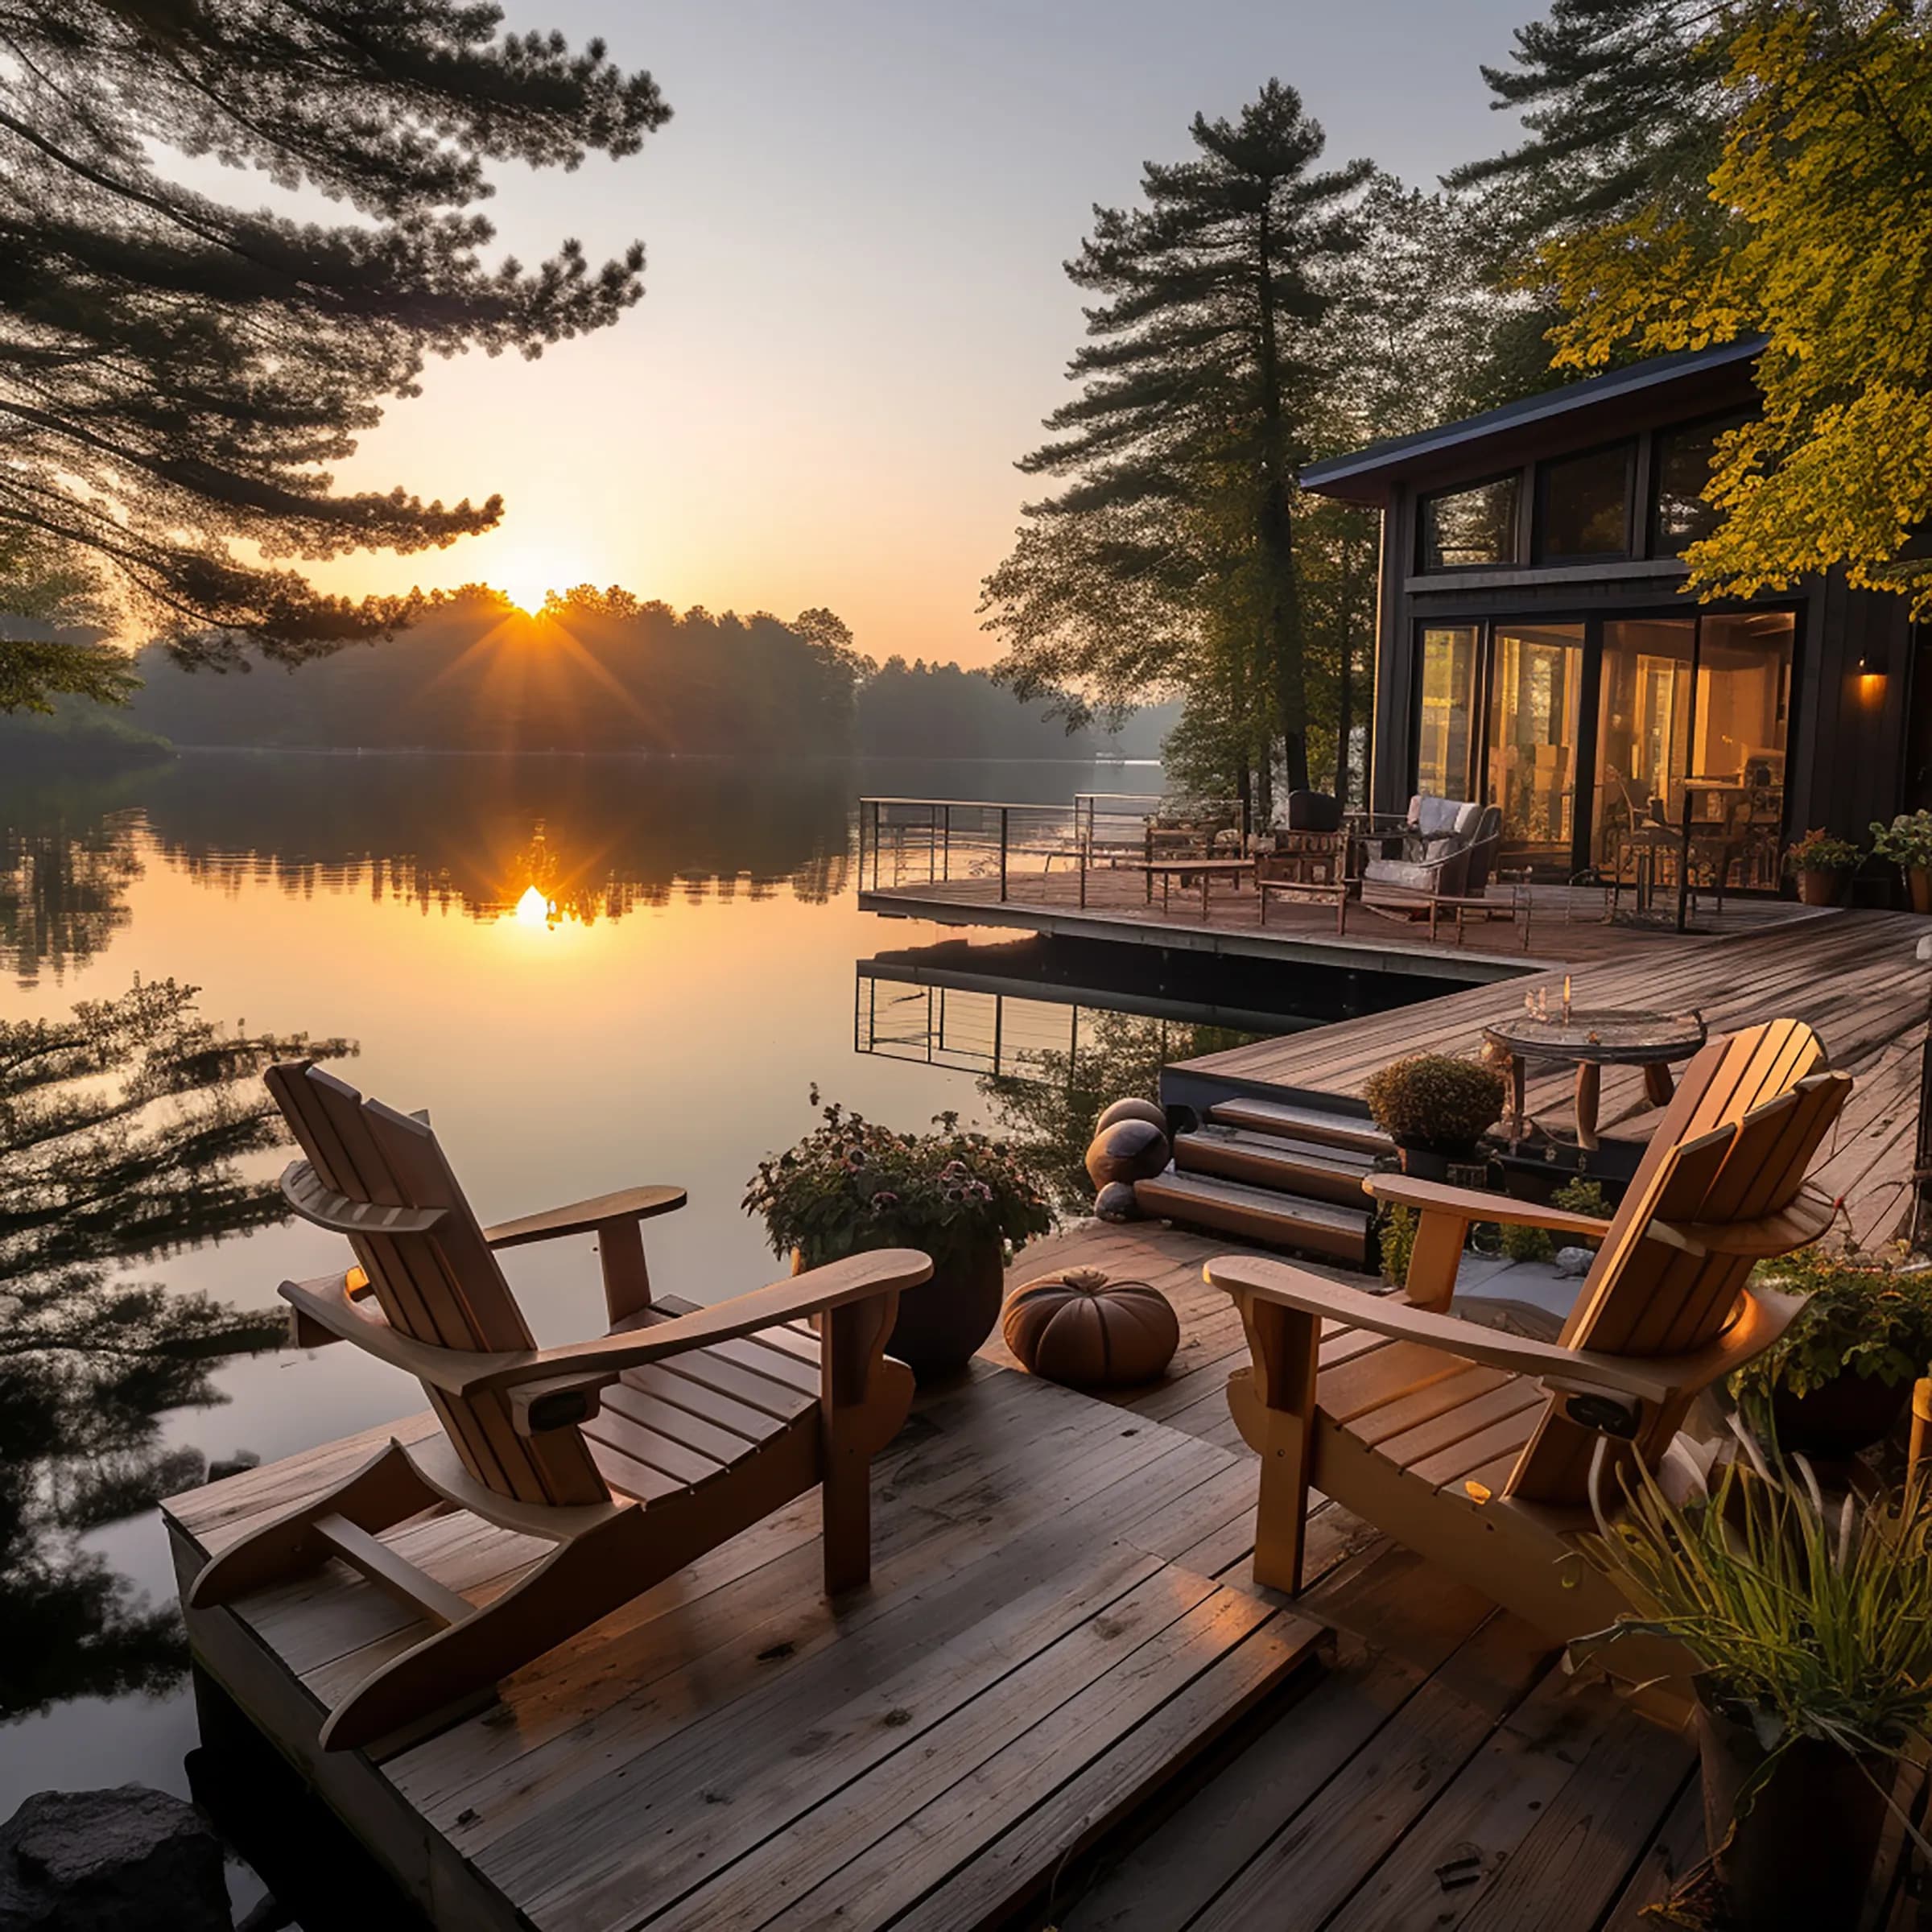
Beach condo, mountain cabin, lake house, second home, the vacation property you want is financeable through a savings club at the same flat-fee rate as a primary residence. No "second home" rate premium. No 25-30% down.
- No down payment
- No rate premium
- No DTI impact
Why traditional financing falls short here.
Mortgage lenders price second homes higher than primary residences, typically 0.25-0.5% above already-elevated rates, often with 25% down required and lower LTV ceilings. Vacation properties end up costing buyers 20-40% more in lifetime financing cost than equivalent primary residences. A savings club ignores that asymmetry entirely.
- Second-home mortgage rates are typically 0.25-0.5% higher than primary residences.
- 25% down payment is standard on vacation/second-home loans.
- Some lenders cap second-home LTV at 75%, locking out otherwise-qualified buyers.
- Rental-income proof is required by some lenders to qualify the property.
- Dual-mortgage exposure raises your DTI ratio and constrains future borrowing.
HOW IT WORKS FOR VACATION PROPERTIES
Four steps to owning.
- 1
Pick your vacation-property value range.
Beachfront condo, mountain cabin, lake house, savings clubs configured by value bracket.
- 2
Join a club, no down payment.
Monthly contributions only. No second-home rate premium. No down-payment requirement.
- 3
Receive your voucher.
Use it with any licensed real-estate agent or direct seller to acquire your vacation property.
- 4
Use your voucher.
It becomes a loan. Savings Club is the lender and the lienholder on the property until the loan is repaid. No mortgage, no PMI, no DTI impact on your primary borrowing capacity.
SAME MATH AS A PRIMARY RESIDENCE
No second-home premium, no DTI loading.
Lenders charge more for a second home and let it load your DTI, constraining your primary borrowing capacity. A savings club ignores that asymmetry. When you use your voucher, it becomes a loan. Savings Club is the lender and the lienholder on the property until the loan is repaid, with no mortgage and no impact on how much you can borrow elsewhere.
- Title transfers at voucher use. Savings Club is the lender and the lienholder on the property until the loan is repaid. No mortgage, no PMI.
- Rent it on AirBnB or Vrbo, leave it empty, or use it yourself.
- Contributions held in irrevocable trust at US Bank.
WHAT YOU GET
The difference.
Any second home
Beach, mountain, lake, urban, configured by value bracket, not property location.
No down payment
Monthly contributions only. Conserve cash for furnishings + travel.
Same flat fee
No "second home" rate premium. Same flat-fee math as a primary residence.
Use or rent flexibility
Once you take title via the voucher, rent it on AirBnB / Vrbo, leave it empty, or use it yourself.
No DTI impact
Club obligation does not load your primary mortgage borrowing capacity the way a second mortgage does.
Trust-protected funds
Contributions held in irrevocable trust at US Bank.
THE MATH, SIDE-BY-SIDE
A $500,000 vacation home, two ways to pay.
| Traditional financing | Savings.Club | |
|---|---|---|
| Down payment on $500,000 vacation home | $125,000 (25%) | $0 |
| Total cost over the term | $1,150,000+ (30y at 7.5%) | $575,000 to $600,000 |
| Compound interest paid | $650,000+ | $0 |
| DTI impact on primary mortgage | Yes | No |
| Lien on title | Yes (bank, 30 years) | Yes (Savings Club, until the loan is repaid) |
Illustrative: $500K vacation home, 30-year second-home mortgage at 7.5% vs. flat-fee Savings.Club obligation. Actual savings vary by property value and term.
QUESTIONS
Common questions.
Yes. Once you take title via the voucher, you can rent it short-term, long-term, or use it yourself. Standard local zoning + STR rules apply.
Be first in line.
Join the waitlist and we'll email you the moment this club opens in your state.
Available in TX, FL, MA, and CT.