Buy an aircraft. Without surrendering it to a bank for 20 years.
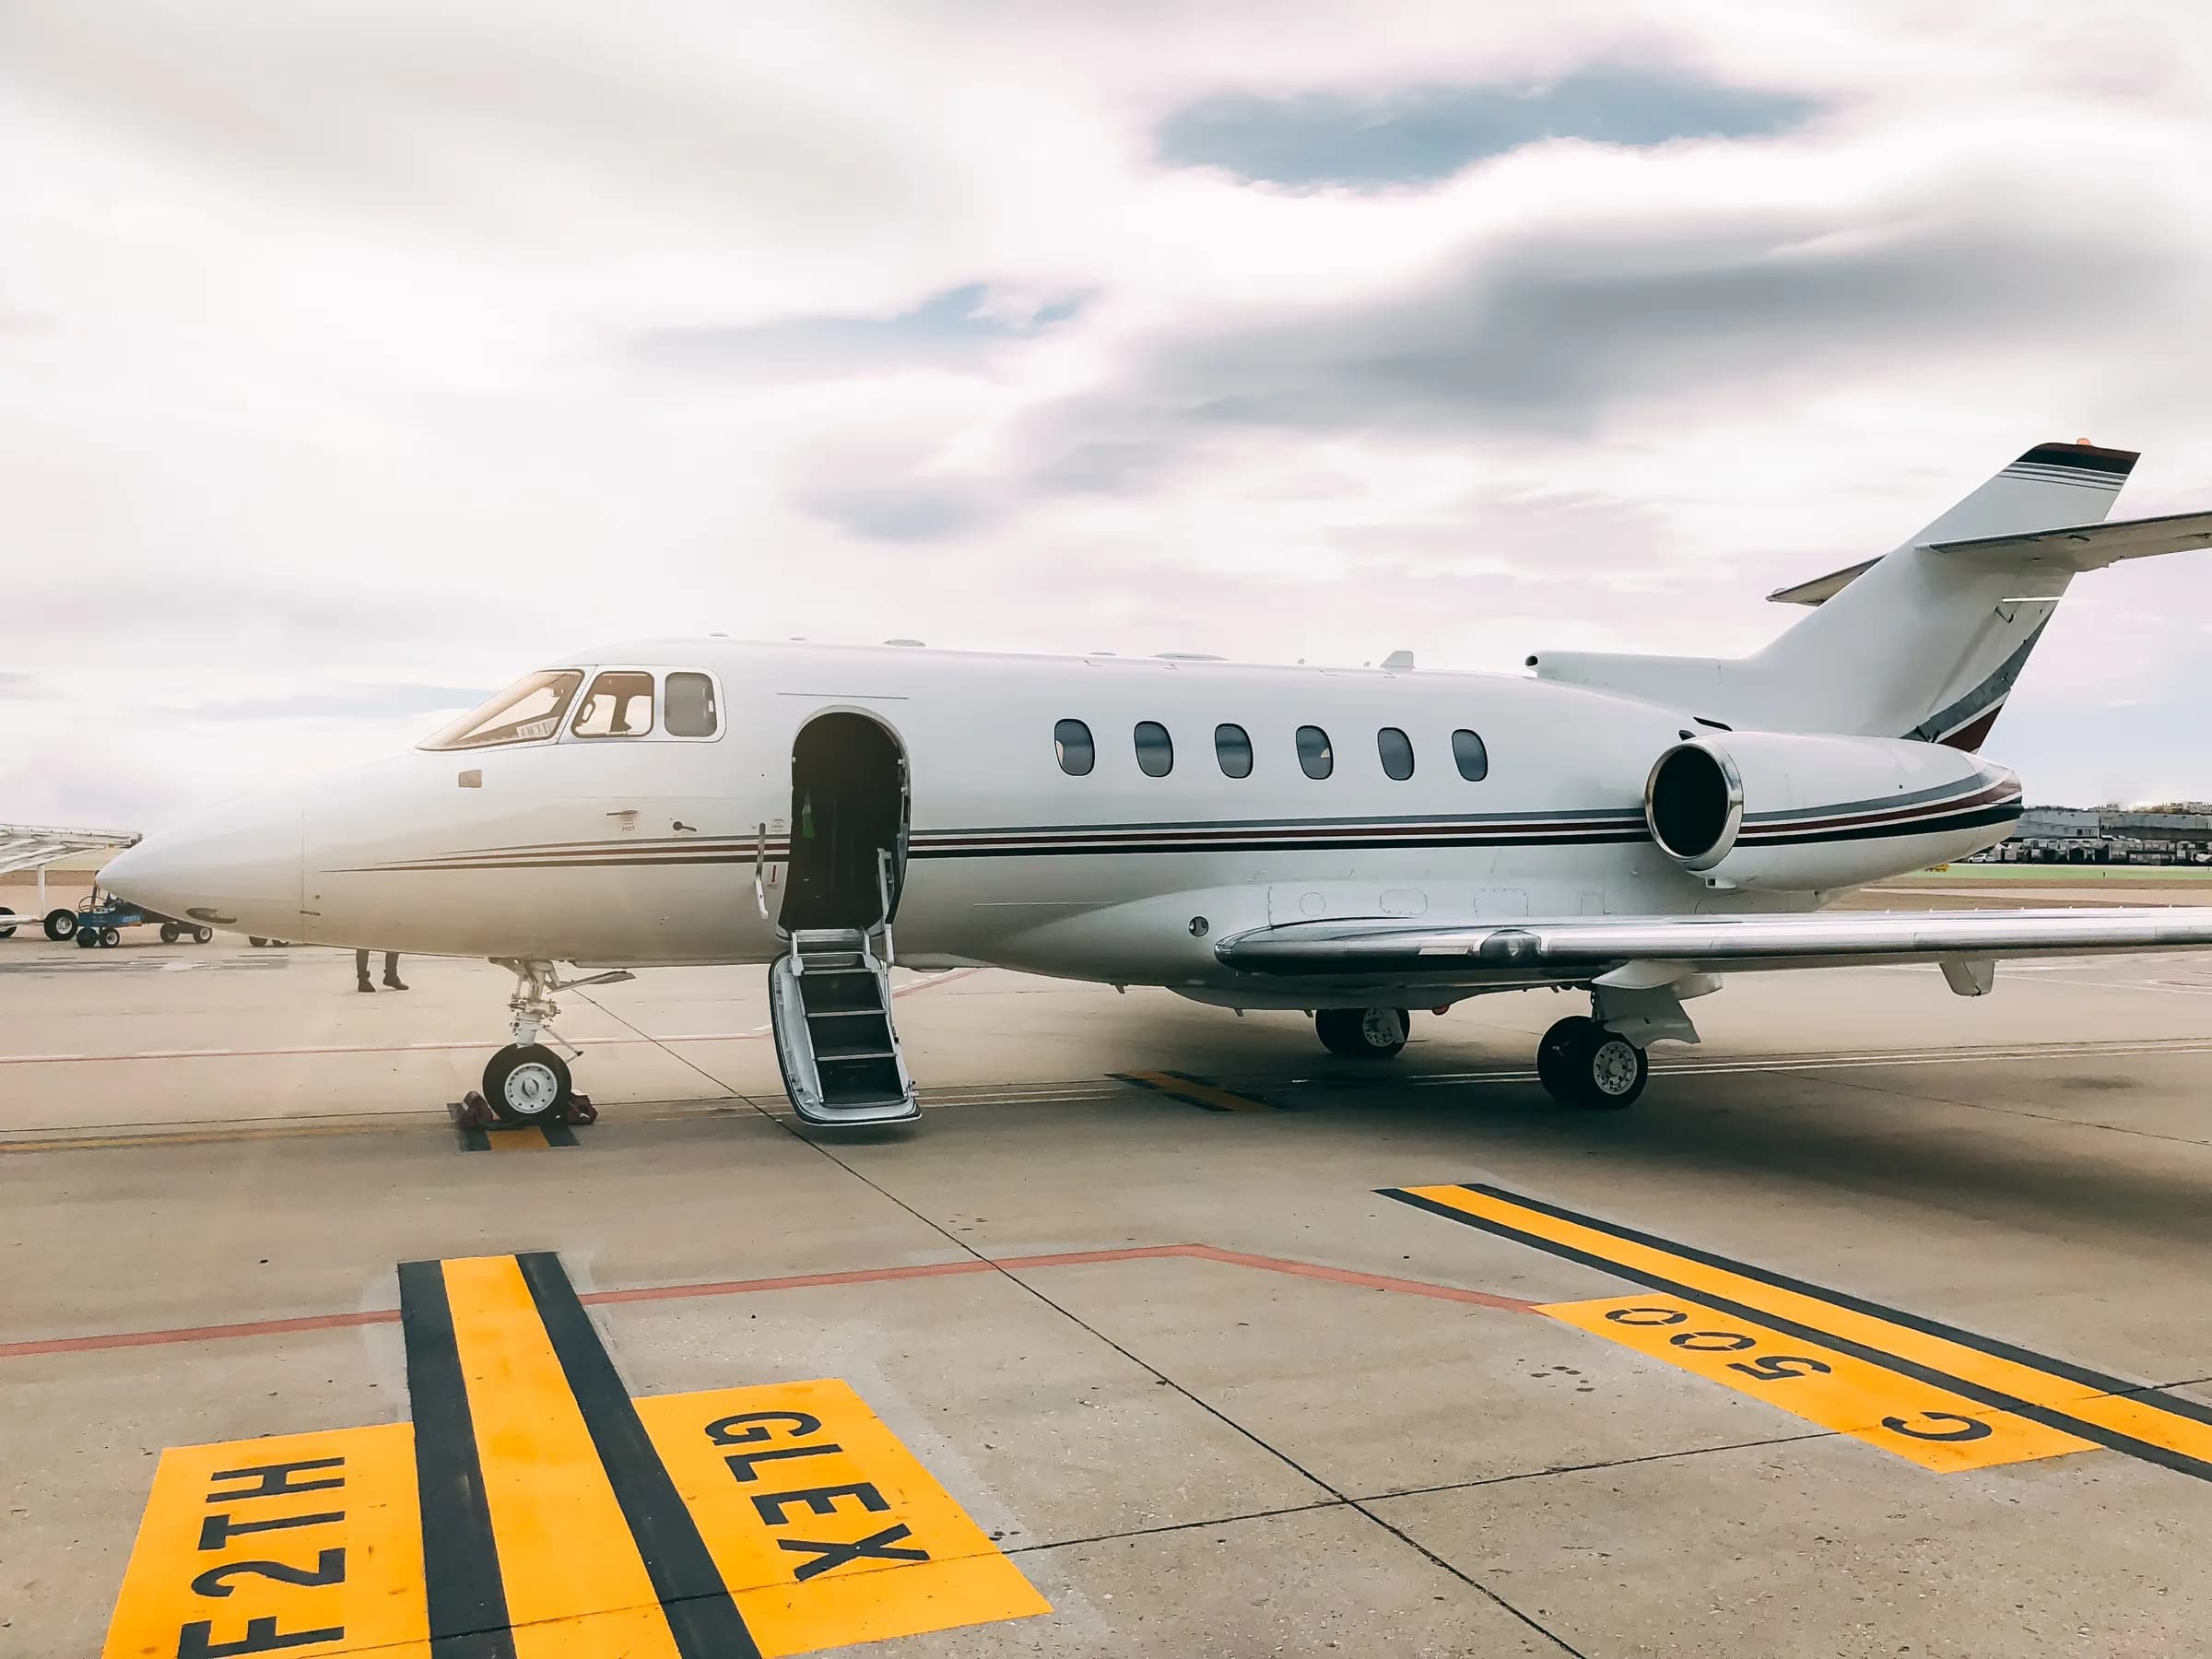
Light aircraft, turboprops, and small business jets cost $200K-$5M+. Traditional aviation lending requires 20-30% down, 5-15 year terms at 8-12% APR, and exposes the airframe as collateral. A savings club replaces the loan with a flat fee, no compound interest, no balloon, no surprises.
- No down payment
- Flat fee
- Savings Club is the lienholder
Why traditional financing falls short here.
Aviation financing is the most expensive consumer-grade lending product in the United States. Lenders price the long airframe lifecycle, partial illiquidity, and uncertain residual values into rate sheets that make every annual inspection feel like a margin call. Savings clubs solve the financing problem the way pilots already solve maintenance: with predictable, flat-fee, member-pooled capital.
- Aviation loans typically run 8-12% APR, 200-400 bps over comparable auto loans.
- 20-30% down required on most light aircraft and twin-engine purchases.
- Balloon payments at year 5 or 10 are standard, refinance risk built in.
- Lender-required insurance + maintenance reserve agreements add ~$3K-$8K/yr in soft costs.
- Selling the aircraft mid-loan triggers prepayment penalties and lien-release delays.
HOW IT WORKS FOR AIRCRAFT
Four steps to owning.
- 1
Pick your aircraft tier.
Single-engine piston, twin, turboprop, or light jet. The savings club is structured around the value bracket of the airframe class you want.
- 2
Join the club.
Members pool monthly contributions into the same trust at US Bank. No down payment. No interest, one flat fee. The total cost is known on day one.
- 3
Receive your Purchasing Voucher.
On a predictable selection cadence, members receive vouchers for the full aircraft value. Use yours at any FAA-licensed dealer or private seller.
- 4
Take title to the airframe.
When you use your voucher, it becomes a loan. Savings Club is the lender and the lienholder on the airframe until the loan is repaid. No balloon. No prepayment penalty. You continue club contributions until your obligation is fulfilled.
NO BALLOON, NO MARGIN CALL
Flat-fee capital, the way pilots already run maintenance.
Aviation lenders build balloon payments and rate-cycle risk into every deal. A savings club replaces the loan with linear contributions to a total club obligation. No 5-or-10-year balloon, no maintenance-reserve escrow. Savings Club, not a bank, is the lender and the lienholder on the airframe until the loan is repaid.
- No 5-or-10-year balloon refinance. Linear contributions to total obligation.
- No bank-mandated escrow for engine overhauls or annual inspections.
- Contributions in an irrevocable trust at US Bank under Jackson Hole Trust Company.
WHAT YOU GET
The difference.
Any FAA-airworthy airframe
Single-engine, twin, turboprop, light jet, savings clubs are configured per value bracket, not per make.
No down payment
Monthly contributions only. Conserve cash for the always-larger-than-budgeted operating bills.
Flat fee, known on day one
No compound interest. No rate-cycle exposure. Your total cost is set when you join.
No balloon refinance
No 5-or-10-year balloon. The structure is linear contributions to total club obligation.
No maintenance-reserve clause
No bank-mandated escrow for engine overhauls, prop overhauls, or annual inspections.
Trust-protected funds
Member contributions sit in an irrevocable trust at US Bank under Jackson Hole Trust Co.
THE MATH, SIDE-BY-SIDE
A $400,000 airframe, two ways to pay.
| Traditional financing | Savings.Club | |
|---|---|---|
| Down payment on $400,000 aircraft | $80,000 to $120,000 | $0 |
| Total cost over the term | $520,000 to $620,000 | $460,000 to $480,000 |
| Compound interest paid | $120,000 to $220,000 | $0 |
| Balloon refinance risk | Yes | No |
| Lien on airframe | Yes (bank) | Yes (Savings Club, until the loan is repaid) |
Illustrative comparison: $400K airframe, 12-year term, 9% APR aviation loan vs. flat-fee Savings.Club obligation. Actual savings depend on aircraft value, term, and current loan-rate environment.
QUESTIONS
Common questions.
Most FAA-certified airframes intended for personal or business use qualify, including single-engine piston, twin-engine, turboprop, and light business jet. Helicopters and experimental category are evaluated case-by-case.
Be first in line.
Join the waitlist and we'll email you the moment this club opens in your state.
Available in TX, FL, MA, and CT.